Home Owner
A 2.75% mortgage from 2021 can feel like a cage once you've outgrown your house. Here's what the math actually looks like, and the real options homeowners have besides just staying put.
A companion piece to our How to Buy a House in the US series and our earlier look at seller's vs. buyer's markets in Southern California — this one is written for the other side of that equation: current homeowners who did everything right in 2021 and now feel trapped by it.
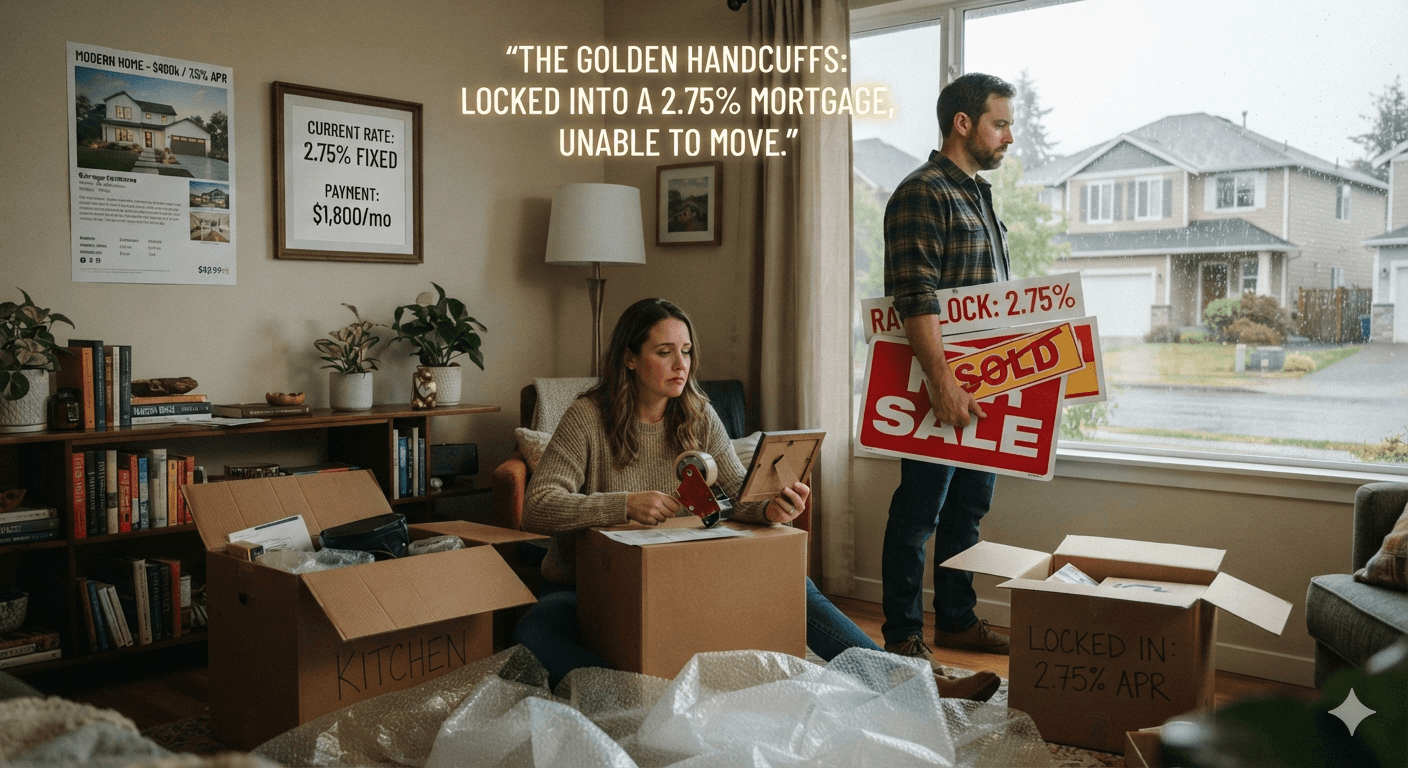
Grace and Min refinanced their Cerritos house in the spring of 2021, locking in a 2.75 percent rate that felt, at the time, like a minor administrative win — a few hundred dollars a month saved, nothing more. Four years and two kids later, that "minor" win has become the single biggest factor in their entire housing decision. Their three-bedroom house, comfortable for a couple, is a genuine squeeze for a family of four, and every time they've run the numbers on moving to something bigger, the math has stopped them cold.
Their current monthly principal and interest payment is a little under $2,300. A comparable move up, at today's rates, would run them well over $4,600 for the mortgage alone — more than double, even accounting for the equity they'd roll into a larger down payment. That's not a stretch. That's a different financial life. So they've stayed, feeling simultaneously grateful for the rate and quietly resentful of what it's costing them in space, and they are very far from alone.
This is what's known in the industry as the "lock-in effect," or sometimes, more bluntly, "golden handcuffs" — and it's reshaped the California housing market in ways that go well beyond any one family's living room. This article is about what's actually happening, why, and what real options exist for homeowners in Grace and Min's position, beyond just waiting it out.
Before we begin: every rate, dollar figure, and scenario in this article is an illustrative example based on current national and California-specific data cited at the end of this piece. Your own numbers — your rate, your equity, your local rent comps — will differ. Run the actual math with a loan officer before making a decision.
The Math Behind Why Nobody's Moving
This isn't a feeling — it's measurable, and the scale of it is larger than most people realize. According to Federal Housing Finance Agency data, the share of homeowners with mortgage rates at 6 percent or higher actually surpassed the share with rates at 3 percent or lower sometime in 2025 — a crossover that would have seemed unthinkable a few years earlier, when ultra-low rates were the norm rather than the exception. The average rate on mortgages currently held by homeowners nationally climbed from 3.8 percent in 2022 to 4.4 percent in 2025, and it's still climbing as more of those pandemic-era refinances get diluted by newer, higher-rate borrowers entering the pool.
The payment gap this creates is significant everywhere, but it's especially brutal in California. Nationally, the difference in monthly principal and interest between a 3 percent rate and a 6 percent rate on a median-priced home works out to roughly $577 a month. In California, where home prices run dramatically higher, that same rate gap on a median-priced home translates to roughly $1,211 a month — more than double the national impact, on top of home prices that were already the country's biggest affordability obstacle before rates even entered the picture.
That gap is exactly why California's housing inventory has stayed so tight for so long, a pattern we touched on in our seller's vs. buyer's market piece. It isn't only that fewer people want to sell — it's that a huge number of current owners are actively unable to justify it financially, holding houses that might otherwise be on the market for a growing family, a downsizing retiree, or a first-time buyer trying to get in.
What the Handcuffs Actually Cost, In Real Numbers
Here's Grace and Min's situation laid out in full, example figures throughout. Their current loan balance sits at $560,000 at 2.75 percent, putting their monthly principal and interest at roughly $2,286. If they sold and bought a $950,000 house — a realistic move-up target in their area — with 20 percent down funded largely by their existing equity, they'd be financing $760,000 at a current rate of around 6.1 percent, putting the new principal and interest at roughly $4,606.
That's a monthly increase of about $2,319, or nearly $27,900 a year, just on the mortgage payment — before accounting for the fact that a larger, newer house typically also means higher property tax and insurance. It's not an exaggeration to say the rate alone functions like a second mortgage payment stacked on top of the one they'd already be taking on. Understanding that number precisely — not just sensing that moving would be "expensive" — is the first real step toward deciding what to actually do about it.
In the worked example, roughly how much more per year would Grace and Min pay in mortgage interest alone if they moved up at today's rates?
(a) About $2,800
(b) About $27,900
(c) About $100,000
B
Roughly $27,900 more per year in mortgage interest alone, based on the worked example's monthly increase of about $2,319.
Five Ways Around the Handcuffs
None of these options make the rate gap disappear, but each addresses it differently, and the right one depends heavily on your specific equity, income, and timeline.
A purchase contingency — making your offer on a new home contingent on selling your current one — is the most conservative option, since you're never on the hook for two mortgages at once. The trade-off is real in a competitive market, where sellers often prefer a clean, non-contingent offer, so this typically works best with a firm 30-to-45-day window to get your current home under contract rather than an open-ended contingency.
A bridge loan is a short-term loan secured by your current home's equity, used to fund the new purchase before your existing home actually sells. It removes the contingency problem entirely, letting you make a stronger, cleaner offer on the new house, but it comes with meaningfully higher interest rates and fees than a conventional mortgage, and it only makes sense if you're genuinely confident your current home will sell within a short window.
A HELOC, used to buy and rent rather than sell, is the option that lets you keep your low rate entirely — you draw against your current home's equity for the down payment on a new place, move into the new home, and turn the old one into a rental, with the rental income ideally covering the original mortgage plus the HELOC payment. This is the option worth walking through in detail, because the math doesn't always pencil out the way it sounds like it should — see below.
A cash offer with a rental-back arrangement, done through certain lenders, lets you make a fully competitive cash offer on the new home and rent it back from the lender until your old home sells and you convert to a standard mortgage. It's a useful tool in a fast-moving market, though it depends on lender participation and isn't available everywhere.
Combining resources with family — pooling funds with parents or other relatives, sometimes toward a household that will include them — can turn a math problem that doesn't work individually into one that does, though this obviously depends on family circumstances that not every homeowner has available.
Running the HELOC-and-Rent Math Honestly
This strategy gets pitched as a clean win — keep the rate, keep the house, use the equity — so it's worth actually running the numbers rather than taking that pitch at face value.
Say a homeowner's current house is worth $850,000 with a $500,000 mortgage balance remaining. At a typical 85 percent combined loan-to-value ceiling, that leaves roughly $222,500 in available HELOC capacity. Drawing $150,000 of that toward a new home's down payment, at a HELOC rate around 8.5 percent, adds an interest-only payment of roughly $1,063 a month.
Now add up the total monthly cost of keeping the original home as a rental: the existing mortgage payment (say $2,176 at a 3.25 percent rate), property tax, insurance, the new HELOC payment, and a maintenance reserve. In this example, that total lands around $4,444 a month. If the house realistically rents for $3,500 a month in the current market, that's only about 79 percent coverage — solidly in the range most lenders and advisors would call "likely not viable" without a meaningful monthly contribution from other income.
This isn't a reason to dismiss the strategy — plenty of homeowners are in markets or situations where the coverage math works out fine, especially with a smaller HELOC draw or a higher rent-to-mortgage ratio than this example. It's a reason to run your own specific numbers before assuming the strategy works, rather than after.
The Assumable Mortgage Wildcard
There's one more option that's gained real attention in 2026, though it applies narrowly: assumable mortgages. FHA and VA loans — unlike most conventional mortgages — can be transferred to a buyer along with the seller's original interest rate, and roughly 6 million homes nationally currently carry both an assumable loan and a rate below 5 percent, though most owners of those homes have no idea the option exists.
For a seller, this can be a genuine selling point in a market where buyers are hungry for any rate relief. For a buyer, it's not simple money for nothing: since home prices have risen roughly 54 percent since January 2020, a buyer assuming a 2021-era loan typically needs to cover the full gap between the original loan balance and the current sale price in cash — often $150,000 to $200,000 or more on a mid-priced home — which puts this option out of reach for a lot of the first-time buyers who'd benefit from it most. The transfer process itself can also stretch well past its legally mandated 45-day window, since loan servicers have little financial incentive to move quickly on facilitating a lower-rate transfer.
If you hold an FHA or VA loan and are considering selling, it's worth confirming your loan's assumability with your lender and discussing it with your agent — it may be a more valuable card than you realize, even if it won't work for every buyer who looks at your house.
Which loan types are typically assumable, letting a buyer take over the seller's rate?
(a) FHA and VA loans
(b) All conventional loans
(c) Jumbo loans only
A
FHA and VA loans are typically assumable; most conventional loans are not.
Is the Lock-In Effect Actually Loosening?
There are real signs it's starting to ease, gradually, in 2026. Rates have drifted down slightly from their 2025 highs, hovering around 6.1 percent on average with forecasts suggesting a range between roughly 5.7 and 6.5 percent through the rest of the year — not dramatic relief, but enough to narrow the gap slightly for homeowners sitting on rates in the high 3s or low 4s rather than the 2s. More importantly, industry researchers note that life events simply override the math for a meaningful share of people regardless of rate — a new job, a growing family, a divorce, a retirement, or a health situation doesn't wait for rates to fall, and homeowners in those situations are increasingly deciding the rate gap is a cost worth paying rather than a permanent wall.
None of this means the lock-in effect is over. It means it's a spectrum, not an all-or-nothing constraint, and where you land on it depends on how much your life circumstances are actually pushing you to move versus how much comfort your current rate is buying you to stay.
A Framework for Deciding
Staying and renovating tends to make sense when: your current home has room to be reconfigured or expanded to fit your changing needs, your rate gap is large (2.5 percentage points or more), and there's no urgent life event forcing a decision on a specific timeline.
Selling despite the rate gap tends to make sense when: a genuine life event — job relocation, family size, health, divorce — makes staying impractical regardless of the financial cost, or when your current home's appreciation has built enough equity that the math, while worse than it was, is still workable for your income.
A HELOC-and-rental strategy tends to make sense when: your local rental market genuinely covers your total carrying costs with room to spare, not just close to break-even, and you're financially prepared to be a landlord, including the maintenance and vacancy risk that comes with it.
Waiting tends to make sense when: none of the above feel urgent, and you're comfortable betting that either rates ease further or your equity continues to grow enough to change the math in your favor over the next year or two.
FAQ
Q1. Is the lock-in effect unique to California? No, it's a national phenomenon, but California's high home prices make the dollar impact of any given rate gap significantly larger here than in most other states — roughly double the national average impact on a median-priced home.
Q2. How do I find out if my FHA or VA loan is assumable? Contact your loan servicer directly and ask specifically about assumability — it's not always advertised clearly, and your agent can help you decide whether to market it as a selling point if you're planning to sell.
Q3. Does refinancing ever make sense if I already have a low rate? Generally not, unless you need to pull significant cash out for a specific purpose and the blended cost still beats your alternatives — refinancing out of a well-below-market rate to a current rate is rarely the right move on its own.
Q4. What's the biggest mistake homeowners make when considering the HELOC-and-rental strategy? Assuming rough market rent will comfortably cover costs without actually running the specific numbers — vacancy periods, maintenance, and property management if you're not self-managing all eat into the margin that looks fine on paper.
Q5. Should I wait for rates to drop further before making any decision? It depends entirely on your own timeline and life circumstances. Rates hovering in a fairly narrow band through 2026 means waiting has a real opportunity cost if a life event is already pushing you to move, but little downside if your situation is genuinely flexible.
Back to Magazine