Investor
A California vacation rental often clears a 2 to 3 percent cap rate. Las Vegas and Phoenix can roughly double that. Here's the real math, and the property manager question that decides whether it actually works.
NITU Path, Chapter 7: Grow What You've Built.
In short: A typical California vacation-rental cabin clears a cap rate somewhere around 2 to 3 percent right now. Comparable rental property in Las Vegas or Phoenix can run closer to 4 to 6 percent, sometimes higher in the right submarket, largely because the purchase price is lower and the property tax rate is roughly a third to half of California's. That gap is real and worth taking seriously. It comes with two catches that change the math: California still taxes its residents on that out-of-state income no matter where the property sits, and a property you can't drive by yourself lives or dies on the property manager you hire.
We ran the numbers on a Big Bear Lake vacation cabin in an earlier piece and found a 2.55 percent cap rate, negative cash flow, and a first-year return that trailed a plain S&P 500 index fund even after crediting loan paydown. The obvious next question is whether the same money does better somewhere the purchase price and the property tax bill aren't working against you from day one. Las Vegas and Phoenix are the two markets Southern California investors ask about most, so it's worth running the same math on both.
Why Investors Look Outside California First
Two numbers explain most of the gap. California's effective property tax rate runs around 0.70 to 0.73 percent; Nevada's runs closer to 0.53 percent, and Arizona's closer to 0.48 percent. That's a real, ongoing difference on every single year of ownership, not a one-time saving. The bigger factor is simply price. A comparable rental home costs meaningfully less in Las Vegas or the Phoenix suburbs than in almost any California market, which means the same rent, or even a lower one, represents a larger percentage return on a smaller purchase price.
Las Vegas, by the Numbers
Condos are where the Las Vegas math currently works hardest. Take a Henderson-area condo at $215,000, rented at $1,650 a month, financed as an investment property with 25 percent down and a 7.5 percent rate. That's a $161,250 loan and a monthly principal-and-interest payment of $1,127.48.
Against $19,800 in gross annual rent, the real costs come to about $1,140 in property tax, roughly $1,000 in insurance, an estimated $3,300 in HOA dues, common on Las Vegas condos and worth confirming per building, plus management, maintenance, and vacancy reserves. Net operating income comes out to about $10,005, a 4.65 percent cap rate, nearly double Big Bear's. The mortgage still puts the property about $294 a month negative at today's rate, but that's a considerably smaller gap to close than the Big Bear cabin's roughly $1,894 monthly shortfall.
Worth knowing before assuming short-term rental income could close that gap further: Clark County just tightened enforcement on unlicensed short-term rentals in August 2026, requiring booking platforms to verify a license before processing any reservation. Unlicensed listings can still be advertised, but can no longer take bookings. A licensed short-term rental remains possible in parts of the valley, but it's a narrower, more regulated path than it was a few years ago, and it needs to be confirmed for the specific property before it factors into anyone's return.
Phoenix, by the Numbers
Phoenix rewards picking the right submarket more than almost anywhere else in this comparison. Buckeye, on the metro's west side, currently runs about a 6.02 percent gross yield, a $395,000 typical home value against roughly $1,982 in monthly rent. Chandler and Queen Creek, on the east side, run closer to 4.2 percent on considerably pricier homes. Same metro, nearly two full points of yield apart, purely based on which suburb.
Using the Buckeye numbers, 25 percent down and 7.5 percent financing works out to a $296,250 loan and a $2,071.42 monthly payment. Net operating income comes to about $15,356 a year, a 3.89 percent cap rate, against roughly $8,428 in property tax, insurance, management, maintenance, and vacancy costs combined. The mortgage still leaves the property about $792 a month negative, again smaller than Big Bear's gap, though larger than the Las Vegas condo's.
The Comparison Across All Three Markets
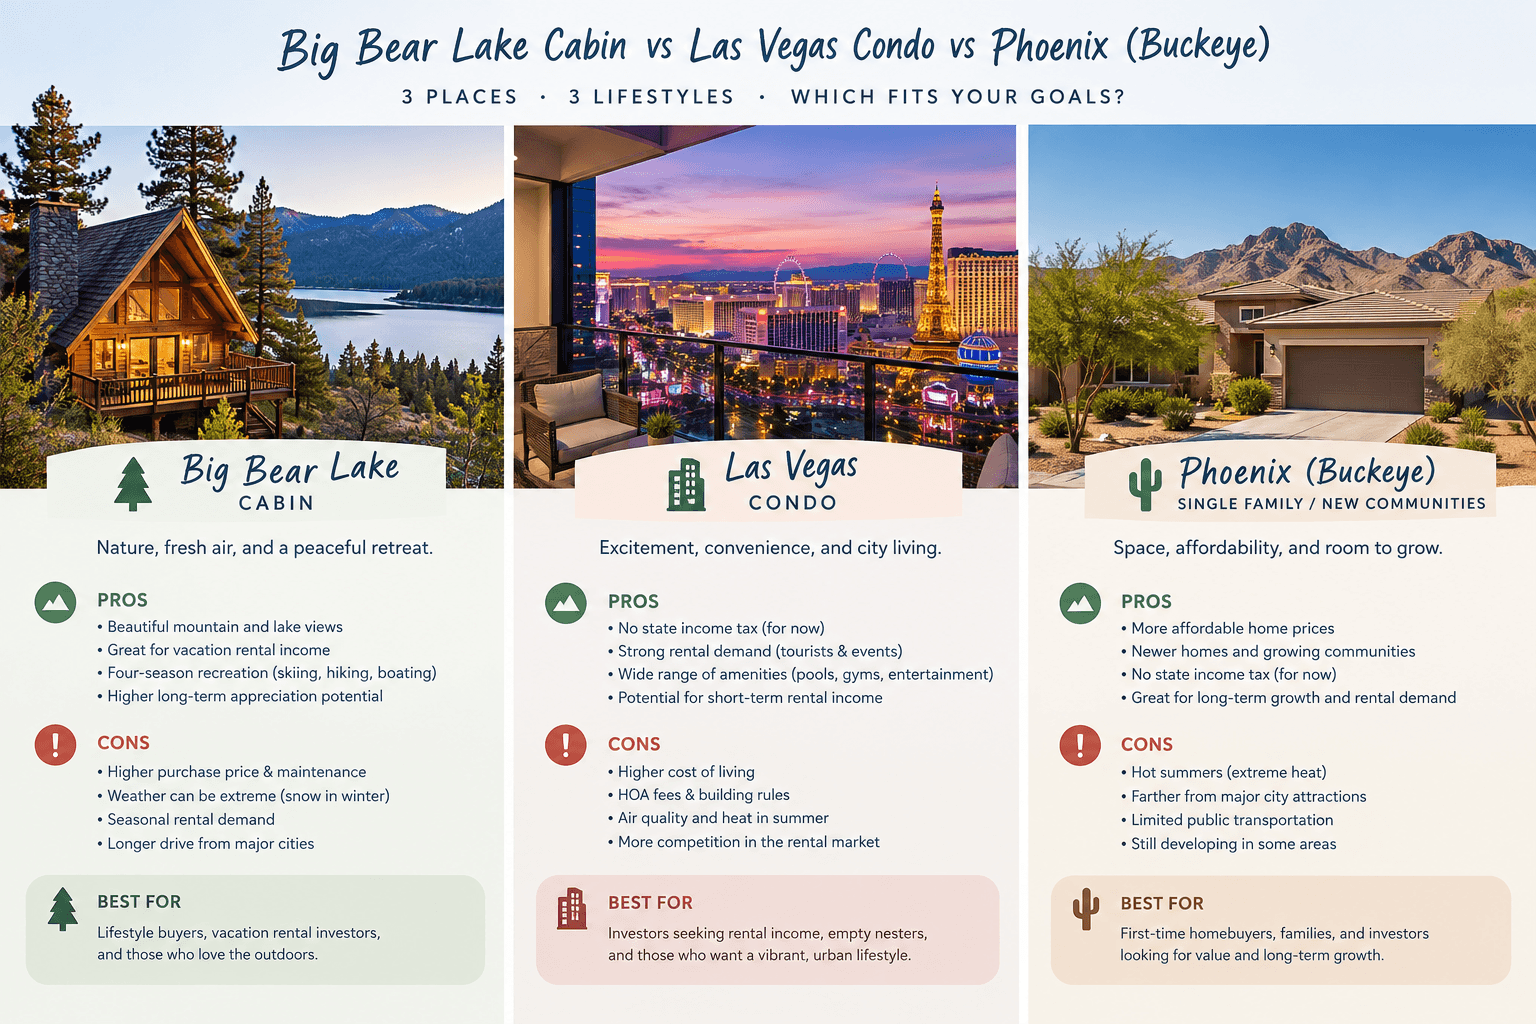
Big Bear Lake cabin | Las Vegas condo | Phoenix (Buckeye) | |
|---|---|---|---|
Purchase price | $545,953 | $215,000 | $395,000 |
Cap rate | 2.55% | 4.65% | 3.89% |
Monthly cash flow after debt service | -$1,894 | -$294 | -$792 |
Every scenario here still runs cash-flow negative once the mortgage is included, because financing an investment property at today's roughly 7.5 percent rate is expensive almost anywhere. The cap rate, which strips out financing entirely, is the fairer way to compare markets against each other, and on that measure, Las Vegas and Phoenix both meaningfully outperform the California vacation-rental cabin.
The Catch: California Still Taxes All of It
This is the part a lot of first-time out-of-state investors miss. California taxes its residents on worldwide income, which explicitly includes rental income from property located in another state. Moving the property to Nevada doesn't move the tax bill; it just changes which state's property tax and insurance rules apply while you own it.
The two states work a little differently from each other on this point. Nevada has no state income tax at all, so there's nothing to credit against, a California resident simply owes California tax on the net rental income, the same as if the property sat in California. Arizona does have its own state income tax, so an Arizona property generally requires a nonresident Arizona return in addition to the California one. California's Schedule S then allows a credit for taxes actually paid to Arizona on that same income, which prevents full double taxation but adds a filing step neither a California nor a Nevada-only rental requires. Either way, the property tax and price advantages that make Las Vegas and Phoenix attractive don't extend to state income tax, and the after-tax return should be run with that in mind rather than assumed away.
Why the Property Manager Matters More Than the Market
None of the numbers above mean anything if the property isn't actually managed well, and that risk goes up considerably once the property is a flight away instead of a drive away.
Both Nevada and Arizona treat property management as regulated brokerage activity. Nevada requires a property management permit as an endorsement on a real estate broker license under state law; Arizona requires a designated broker on file under its own real estate statute. That license is worth confirming directly rather than taking on faith, since it's the baseline that separates a legitimate management company from someone collecting a monthly fee with no real accountability behind it.
Beyond the license, a few things are worth confirming before signing a management agreement on a property you won't be walking through yourself: how quickly they respond to maintenance requests and who actually does the work, how they screen tenants and what their current vacancy rate looks like across their portfolio, what their fee actually covers versus what gets billed separately as a markup on repairs, and how they handle an eviction if it comes to that, since Nevada and Arizona's processes both move differently than California's. A management fee of roughly 8 to 10 percent of rent is standard for long-term rentals in both markets. A fee noticeably below that is worth asking hard questions about, since underpricing management is one of the more common ways a struggling property management company tries to win new accounts right before service quality drops.
Weighing It Honestly
The cap rate gap between California and these two out-of-state markets is real, not a rounding error, and it's a legitimate reason to widen the search beyond California if the goal is genuinely a better-performing investment rather than a place to also use personally. But the gap narrows once California's tax bill on that income is factored in, and it can disappear entirely if the property manager on the other end turns out to be the wrong one. Run the actual cap rate on the specific property, confirm the state income tax picture with a tax professional who handles multi-state returns, and treat the property manager interview with the same seriousness as the purchase itself. That combination, not the market alone, is what actually decides whether an out-of-state purchase outperforms staying closer to home.
Two related paths are worth weighing against this one before committing the down payment. If the funding source for that down payment is equity sitting in a California home rather than fresh cash, it's worth understanding what that equity can actually support first, covered in what your home equity can actually do for you. And for anyone who already owns a California home with a rate worth protecting, converting it into a rental rather than buying new out of state is its own real option, one we've run the numbers on in turning your first home into your first rental property.
Quick Check: Buying Investment Property Out of State
Q1. In the worked examples, roughly what cap rate did the Las Vegas condo produce, compared to the Big Bear Lake cabin?
(a) About 4.65 percent, nearly double Big Bear's 2.55 percent
(b) Roughly the same as Big Bear
(c) About half of Big Bear's cap rate
A
The Las Vegas condo's 4.65 percent cap rate ran nearly double the Big Bear cabin's 2.55 percent.
Q2. (T/F) Once financed at today's investment-property rates, every market examined in this article still produced negative monthly cash flow.
T — Even Las Vegas and Phoenix, with meaningfully better cap rates than Big Bear, still ran cash-flow negative once today's roughly 7.5 percent investment-property financing was included.
Q3. What changed in Clark County, Nevada in August 2026 regarding short-term rentals?
(a) All short-term rentals were banned outright
(b) Booking platforms must verify a license before processing a reservation at a property
(c) Short-term rental permits became unlimited
B
Clark County's new ordinance requires booking platforms to verify a property's license before processing reservations, targeting unlicensed short-term rentals without banning licensed ones.
Q4. Does moving rental property to Nevada eliminate a California resident's state income tax on that rental income?
(a) Yes, entirely
(b) No, California taxes residents on worldwide income regardless of where the property is located
(c) Only if the property is held in an LLC
B
California taxes its residents on worldwide income, which includes rental income from property located in any other state.
Q5. How does Arizona rental income differ from Nevada rental income for a California resident, tax-wise?
(a) There's no difference at all
(b) Arizona generally requires a nonresident Arizona return, with a California credit for taxes paid to Arizona; Nevada has no state income tax to file at all
(c) Arizona rental income is entirely tax-free
B
Arizona's own state income tax generally requires a nonresident return, with California's Schedule S crediting taxes paid to Arizona; Nevada has no state income tax at all, so only the California return applies.
Q6. What do both Nevada and Arizona require of property management companies?
(a) Nothing; property management is unregulated in both states
(b) A regulated broker license or endorsement covering property management activity
(c) A minimum of 10 years in business
B
Nevada requires a property management permit as an endorsement on a broker license, and Arizona requires a designated broker on file, treating property management as regulated brokerage activity in both states.
About the author: I'm a licensed real estate agent practicing in California. This article is part of NITU Path, Chapter 7, a series written to walk buyers through their entire homeownership journey.
This article is for general informational and educational purposes only and is not financial, tax, or legal advice. Rental income, mortgage rates, property tax rates, and licensing requirements vary by property and change over time. Consult a licensed tax professional familiar with multi-state returns, a local lender, and a property manager before treating any out-of-state property as an investment.
Sources:
Nevada Real Estate Group — Nevada Property Taxes vs. California, Oregon, and Washington
Fox5 Las Vegas — Clark County Crackdown on Unlicensed Short-Term Rental Platforms
California FTB — 2025 Instructions for Schedule S, Other State Tax Credit
50 State Brokerage — Property Management License Requirements by State
Back to Magazine